Giving Inheritance While You Are Still Living: The 2026 Tax Playbook Families Are Asking About

Should I give my children their inheritance now or later?
The short answer on giving inheritance while living: In 2026 you can give up to $19,000 per person in present-interest gifts, to as many people as you like, without filing a gift tax return or paying any tax. (Gifts of future interests, such as most gifts in trust, must be reported on Form 709 no matter the amount.) Married couples can generally double that to $38,000 per recipient, either from each spouse’s own funds or by electing gift splitting on Form 709. Tuition and medical bills paid directly to the school or provider are excluded from gift tax with no dollar limit. Gifts above those amounts simply draw down your $15 million lifetime exemption ($30 million per married couple), so very few families will ever pay federal gift tax. The real tax question is not “will I owe gift tax?” It is “which assets should I give now, and which should my heirs inherit later?”
That second question is where families save, or lose, real money. Below, we answer the questions our tax professionals hear most often, compare the strategies that work best, and walk through a recent client engagement where a Georgia business-owning couple moved more than $1.7 million to their family in a single year without paying a dollar of gift tax.
Key Takeaways for 2026
- Annual gift tax exclusion: $19,000 per recipient for present-interest gifts ($38,000 for married couples giving from each spouse’s funds or electing gift splitting).
- Lifetime gift and estate tax exemption: $15 million per person, made permanent by the One Big Beautiful Bill Act and indexed for inflation after 2026.
- Direct payments of tuition and medical expenses: excluded from gift tax with no dollar limit, and they do not use your annual exclusion.
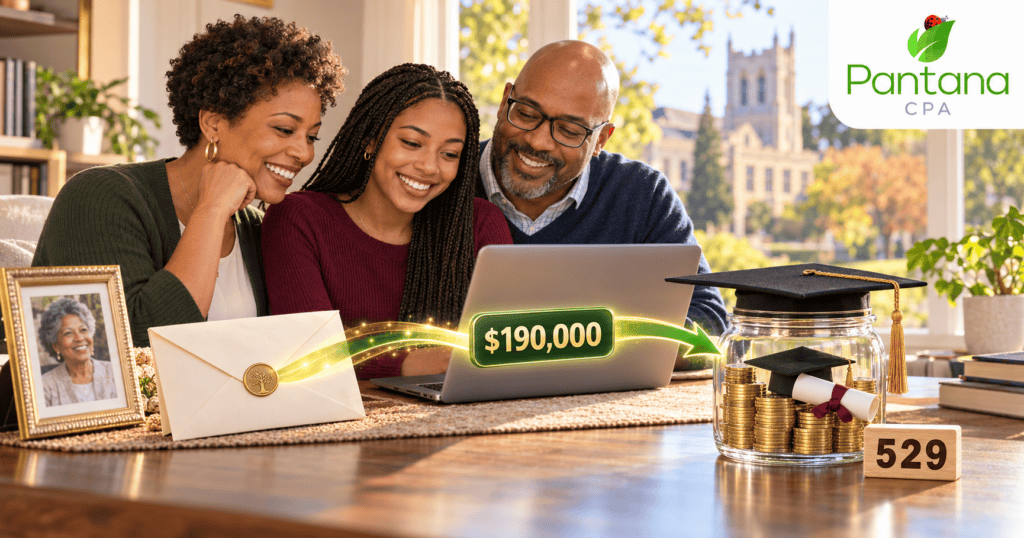
- 529 “superfunding”: up to $95,000 per beneficiary in one year ($190,000 per couple) using a five-year election.
- Gifted assets generally carry over your adjusted cost basis. Inherited assets generally get a stepped-up basis. That difference often matters more than gift tax itself.
- Georgia has no state estate tax and no inheritance tax.
Why More Families Are Giving an Inheritance While They Are Still Alive
The phrase “living inheritance” has moved from estate-planning jargon into ordinary kitchen-table conversation. Parents want to help a child with a first home while mortgage rates still sting. Grandparents want to watch a grandchild graduate debt free instead of leaving money that arrives after the need has passed. Business owners want to bring the next generation into ownership while they are still around to mentor them.
The tax law has made that easier. When Congress passed the One Big Beautiful Bill Act in July 2025, it set the federal estate and gift tax exemption at $15 million per person starting in 2026 and removed the “sunset” that would have cut the exemption roughly in half. The IRS confirmed the 2026 figures in its annual inflation adjustment announcement. The urgency to “use it before you lose it” has eased, but the opportunity to give strategically is larger than ever.
What Is the 2026 Gift Tax Exclusion, and Who Pays the Tax?
The annual exclusion for 2026 is $19,000 per recipient, unchanged from 2025 (see our 2025 gift tax guide). You can give that amount to your son, your daughter-in-law, each grandchild, a neighbor, or anyone else, and none of it counts against your lifetime exemption. There is no limit on the number of recipients. The rule comes from Internal Revenue Code Section 2503(b), and it applies only to gifts of a present interest, meaning the recipient can use or enjoy the gift right away. Gifts to a spouse who is a U.S. citizen are generally unlimited thanks to the marital deduction.
Two points surprise many clients:
- The giver pays any gift tax, not the recipient. The person receiving a gift owes no income tax on it and does not report it on their Form 1040. The IRS spells this out in its Frequently Asked Questions on Gift Taxes.
- Going over $19,000 rarely means writing a check to the IRS. It means filing Form 709 so the excess is subtracted from your $15 million lifetime exemption. Tax is only owed after the entire exemption is used up.
The Best Ways to Give an Inheritance While Living (and Which Work Best)
There is no single best method. The right mix depends on what you own, who you are helping, and whether you need the money back someday. Here are the strategies our team uses most, roughly in the order we usually consider them.
1. Annual Exclusion Gifts of Cash
Best for: Steady, simple transfers with zero paperwork.
A married couple with three children and six grandchildren can move $342,000 a year (9 recipients x $38,000) entirely outside the gift tax system. Include the three children’s spouses (twelve recipients in all) and the number climbs to $456,000. Over ten years that is several million dollars transferred with no Form 709 required, as long as each spouse gives from his or her own funds and stays at or under $19,000 per person. If one spouse’s money funds the whole gift, the couple must elect gift splitting under Section 2513 on Form 709 to reach $38,000, even though no tax is due.
2. Paying Tuition and Medical Bills Directly
Best for: Grandparents helping with college, private school, or major medical costs.
Under Section 2503(e), tuition paid directly to a qualifying educational institution and medical expenses paid directly to the provider are excluded from gift tax with no dollar limit. The key word is directly. Writing a check to your granddaughter so she can pay the bursar does not qualify. Writing it to the university does. Room, board, and books do not count as tuition, so those are better covered with annual exclusion gifts or a 529 plan. Health insurance premiums paid directly to the insurer on someone else’s behalf can qualify as medical expenses, but amounts later reimbursed by insurance do not, as explained in Treasury Regulation 25.2503-6. Keep in mind this is a gift tax exclusion only: the payer gets no income tax deduction because of it.
3. 529 College Savings “Superfunding”
Best for: Front-loading education money for young grandchildren so it grows tax free for years.
Section 529(c)(2)(B) lets you treat a large 529 contribution as if it were made evenly over five years. In 2026 that means one person can deposit $95,000 per beneficiary ($19,000 x 5) and a couple can deposit $190,000, all covered by annual exclusions. You must report the election on Form 709, and you cannot make additional annual exclusion gifts to that same beneficiary during the five-year window without dipping into your lifetime exemption. Earnings grow tax free and come out tax free for qualified education costs, as described in IRS Publication 970. For a full rundown on how 529 plans work alongside education credits, see our 2026 guide to 529 plans and education tax credits. One caveat: if the donor dies during the five-year window, the portion allocable to the years after death is pulled back into the donor’s gross estate under Section 529(c)(4)(C).
Unused 529 money can be rolled into the beneficiary’s Roth IRA, up to $35,000 lifetime, but only if all of these conditions are met under Section 529(c)(3)(E):
- The 529 account has been open for at least 15 years.
- The amount rolled over comes from contributions (and their earnings) made more than five years before the rollover.
- The money moves in a direct trustee-to-trustee transfer to a Roth IRA in the beneficiary’s name.
- The rollover fits within the beneficiary’s annual Roth IRA contribution limit for that year, reduced by any other IRA contributions, and the beneficiary has enough earned income to support it.
4. Gifting Interests in a Family Business
Best for: Owners of S corporations, LLCs, and partnerships planning succession.
Giving non-voting shares or minority LLC units lets the next generation share in future growth while you keep control. Because a minority, non-marketable interest is worth less to an outside buyer, a qualified appraisal often supports valuation discounts that let you transfer more economic value per dollar of exemption used. Every dollar of growth after the gift happens outside your estate. Discounts are fact-specific, subject to the special valuation rules in Chapter 14 of the Internal Revenue Code (Sections 2701 to 2704), and frequently examined by the IRS. These gifts require a qualified appraisal and an adequately disclosed Form 709 so the IRS statute of limitations begins to run. See the IRS Instructions for Form 709 for the adequate disclosure rules.
5. Intrafamily Loans
Best for: Helping a child buy a home or start a business when you want the money back.
A properly documented loan is not a gift if it charges at least the Applicable Federal Rate (AFR) that the IRS publishes monthly in revenue rulings under Section 1274(d). Those rates are usually well below what a bank charges. You can later forgive annual payments using your $19,000 exclusion. The loan needs a signed note, a repayment schedule, and actual payments, or the IRS may treat the whole amount as a gift. If you would rather let a family member live in a property you own, read our guide to renting a home to a family member.
6. Lifetime Gifts Above the Annual Exclusion (Using Your $15 Million Exemption)
Best for: Families with estates that may exceed the exemption, or assets expected to appreciate quickly.
Large gifts made now remove all future appreciation from your estate. Treasury’s anti-clawback regulation at Treasury Regulation 20.2010-1(c) generally protects gifts sheltered by the basic exclusion amount in effect on the gift date, even if the exclusion later falls, by computing the estate tax credit using the gift-date amounts. (The rule addresses the basic exclusion amount, not a deceased spouse’s unused exclusion, or DSUE.) For most families under $15 million, large lifetime gifts are a choice about timing and control, not a tax necessity.
The Hidden Tax Trap: Cost Basis and the Step-Up
This is the part of the conversation that changes the most plans. When you give an asset during your life, the recipient generally takes over your adjusted cost basis (with special rules if the asset has lost value) under Section 1015. When your heirs inherit that same asset at your death, the basis generally “steps up” to its fair market value on the date of death under Section 1014.
Here is what that looks like in dollars. Suppose you bought a rental house in 1998 for $140,000 and it is now worth $610,000.
- Gift it today and your daughter’s basis is $140,000. If she sells for $610,000, she reports a $470,000 gain. At the 15% federal long-term capital gains rate, that is roughly $70,500 in federal tax before any state tax, net investment income tax, or depreciation recapture.
- Leave it to her at death and her basis resets to about $610,000. If she sells soon after, the taxable gain is close to zero.
The rule of thumb our CPAs use: give cash and high-basis assets during life. Hold low-basis, highly appreciated assets until death. IRS Publication 551, Basis of Assets, covers both rules in detail. Retirement accounts follow different rules: an inherited IRA does not get a step-up in basis, and most beneficiaries face withdrawal deadlines. Our inherited IRA update explains what heirs need to know.
Comparison: Which Living Inheritance Options Work Best?
| Strategy | 2026 Limit | Form 709 Needed? | Best Use |
|---|---|---|---|
| Annual exclusion gifts | $19,000 per recipient ($38,000 per couple) | No, unless splitting gifts | Simple yearly cash gifts |
| Direct tuition payments | Unlimited | No | College and private school |
| Direct medical payments | Unlimited | No | Surgeries, insurance premiums |
| 529 superfunding | $95,000 per beneficiary ($190,000 per couple) | Yes | Young grandchildren |
| Business interest gifts | Uses lifetime exemption above $19,000 | Yes, with appraisal | Succession planning |
| Intrafamily loan at AFR | No limit if properly documented | Only for forgiven amounts over $19,000 | Home purchases, startups |
| Large lifetime gifts | $15 million per person | Yes | Estates near or above the exemption |
Case Study: How a Georgia Distribution Company Owner Moved $1.78 Million to His Family in One Year, Gift Tax Free
Client details are a composite and names have been changed to protect confidentiality. Figures reflect 2026 tax law.
When “Ray and Linda” first sat down with our team in February 2026, Ray had just turned 68. He had spent 31 years building a plumbing and HVAC parts distribution company in metro Atlanta, an S corporation an independent appraiser had valued at $4.2 million. The couple had three adult children, one of whom already ran the warehouse, and seven grandchildren ranging from age 2 to age 19.
Their goal was plain: “We want to see them enjoy it.” Their worry was just as plain. A friend had told Linda that giving more than $19,000 meant a 40% tax bill.
It did not. Gift tax is computed on a cumulative, progressive schedule (top rate 40%) under Section 2502 and Section 2001(c), and only after the lifetime exemption is used up. In 2026 a married couple would have to make more than $30 million of taxable gifts before any tax was due. Here is the plan our CPAs built and carried out over the 2026 tax year:
- Cash gifts to the three children: $38,000 each (Ray and Linda each gave $19,000), for $114,000. No Form 709 needed for these gifts because each spouse wrote a separate check.
- 529 superfunding for the four youngest grandchildren: Ray and Linda each contributed $95,000 per grandchild and each made a five-year election, for $190,000 per grandchild and $760,000 in total. That money now has 10 to 16 years to compound tax free before the first freshman tuition bill.
- Direct tuition for the oldest grandchild: A $28,400 check sent straight to her university’s bursar for the 2026-2027 academic year. Unlimited exclusion, no Form 709, and it did not touch her annual exclusion.
- Gift of non-voting S corporation stock: The company, whose shares Ray and Linda held together, was recapitalized into voting and non-voting shares. The couple gave a 30% non-voting interest to the three children, with each spouse giving half from his or her own shares. On a $4.2 million value, 30% is $1,260,000 before discounts. The appraisal applied a combined 30% discount for lack of control and marketability, a fact-specific determination under the Chapter 14 valuation rules that must be supported by a qualified appraisal and adequately disclosed, since discounts in family-entity transfers are frequently examined. That put the gift at $882,000, or $441,000 against each spouse’s $15 million exemption. Ray kept 100% of the voting control.
- What they did not give: A rental duplex bought in 1998 for $140,000 and now worth about $610,000. Gifting it would have passed along a $470,000 built-in gain. Keeping it in their estate preserves the step-up in basis for their children, a potential federal capital gains savings of roughly $70,500.
The result: $1,784,400 moved to the next two generations in 2026. Federal gift tax owed: $0. Lifetime exemption used: $441,000 each, leaving Ray and Linda with roughly $29.1 million of combined exemption, far more than their remaining estate. Georgia gift tax: none, because Georgia does not impose one. Future growth on the gifted stock and the 529 accounts now builds outside their estate.
Our team prepared two adequately disclosed Form 709 returns, one for each spouse, reporting each spouse’s half of the stock gift and each spouse’s $95,000-per-grandchild 529 five-year election, with the full appraisal attached. Both are calendared for filing by April 15, 2027, with each spouse’s Form 709 filed separately from the couple’s joint Form 1040. Ray summed it up at our last meeting: “I thought we’d be writing the IRS a check. Instead, I watched my son sign his first shareholder agreement.”
Not sure if your books are on track for tax season?
Schedule a call to review where things stand and what needs attention before small issues become bigger ones.
Gift Tax Return Rules: When You Must File Form 709
You must file Form 709 for any year in which you:
- Give more than $19,000 to any one person (other than tuition or medical payments made directly).
- Split gifts with your spouse, even if each half is under $19,000.
- Make a 529 five-year election.
- Give a “future interest,” such as most gifts to trusts, in any amount.
- Give more than $194,000 in 2026 to a spouse who is not a U.S. citizen. Because the unlimited marital deduction is not available for gifts to a non-citizen spouse under Section 2523(i)(1), this special exclusion under Section 2523(i)(2) is the only protection below the lifetime exemption. Amounts above it reduce your lifetime exemption.
Form 709 is due April 15 of the year after the gift. It is extended along with your individual income tax return only if you file Form 4868 to extend that return. If you file your Form 1040 on time, or forgot the gift return, you can request a standalone automatic six-month extension for Form 709 using Form 8892. Each spouse files separately; there is no joint gift tax return. Details are in the official Form 709 instructions.
Does Georgia Have a Gift, Estate, or Inheritance Tax?
No. Georgia does not tax gifts, estates, or inheritances. According to the Georgia Department of Revenue Estate Tax FAQ, Georgia’s former estate tax applies only to estates of people who died before January 1, 2005, because it was tied to a federal state death tax credit that was repealed. Georgia then formally eliminated the estate tax effective July 1, 2014 (O.C.G.A. Section 48-12-1). For Georgia families, federal rules are the only transfer taxes in play. If you own property in another state, check that state’s rules separately, since a handful still impose estate or inheritance taxes.
Other Questions to Ask Before You Give
- Will I need this money back? Gifts are permanent. Keep enough to cover retirement, long-term care, and emergencies. Our guide to OBBBA tax relief for seniors covers the new deductions for taxpayers 65 and older.
- Could Medicaid eligibility matter? Medicaid reviews gifts made within five years before applying for long-term care coverage. The look-back rule is in 42 U.S.C. Section 1396p.
- Does the kiddie tax apply? Investment income on assets given to a child under 19 (or a full-time student under 24) may be taxed at the parent’s rate. See IRS Topic No. 553.
- Is the recipient ready? For minors or young adults, a custodial account, 529 plan, Trump Account, or trust often works better than an outright gift.
- Does my will and estate plan still match? Large lifetime gifts can unintentionally make an inheritance unequal among children. Coordinate with your estate planning attorney.
Frequently Asked Questions About Giving an Inheritance While Living
How much money can I give my children tax free in 2026?
You can give each child up to $19,000 in present-interest gifts in 2026 without filing a gift tax return. A married couple can give $38,000 per child, either from each spouse’s own funds or by electing gift splitting on Form 709. Amounts above that are reported on Form 709 and reduce your $15 million lifetime exemption, but no tax is due unless you have used up the full exemption.
Does my child have to pay taxes on money I give them?
No. The person receiving a gift does not owe federal income tax or gift tax on it and does not report it on their tax return. If any gift tax were ever owed, the giver would pay it. Future income the gift earns, such as interest or dividends, is taxable to the recipient.
Is it better to give an inheritance now or leave it in my will?
It depends on the asset. Cash and assets that have not grown much in value are usually better to give during life, because future growth leaves your estate. Highly appreciated assets like real estate or long-held stock are often better left at death, because heirs receive a stepped-up cost basis that can wipe out capital gains tax.
What happens if I give more than $19,000 to one person?
You file Form 709 by April 15 of the following year. The amount over $19,000 is subtracted from your lifetime exemption, which is $15 million per person in 2026. You only pay gift tax after your total lifetime taxable gifts exceed that exemption.
Can I pay my grandchild’s college tuition without using my gift exclusion?
Yes. Tuition paid directly to a qualifying school is excluded from gift tax with no dollar limit, and it does not use your $19,000 annual exclusion. The payment must go straight to the institution, and it covers tuition only, not room, board, or books.
What is 529 superfunding?
529 superfunding lets you contribute five years of annual exclusion gifts to a 529 plan at once. In 2026 that is up to $95,000 per beneficiary, or $190,000 for a married couple, with no gift tax. Each donor files Form 709 to make the five-year election. If the donor dies within the five years, the portion allocable to the years after death is included in the donor’s estate.
Does Georgia have an inheritance tax or gift tax?
No. Georgia does not impose a gift tax, an estate tax, or an inheritance tax. Georgia residents only need to plan around federal gift and estate tax rules.
Do married couples file a joint gift tax return?
No. There is no joint Form 709. Each spouse who makes a reportable gift or elects to split gifts files their own return.
How Pantana CPA Helps Families Plan a Living Inheritance
Since 2002, Pantana CPA has helped individuals, families, and business owners across Georgia and nationwide turn good intentions into a tax-smart plan. For living inheritance work, our team:
- Maps your assets by cost basis to identify what to give now and what to hold.
- Models annual exclusion, 529, tuition, and business-interest gifting over multiple years.
- Coordinates with your appraiser and estate planning attorney.
- Prepares and files adequately disclosed Form 709 gift tax returns.
- Tracks lifetime exemption usage year over year so nothing is lost or double counted.
If you are thinking about helping your children or grandchildren now rather than later, the best time to talk with a tax professional is before the first check is written.
Say goodbye to tax surprises.
Subscribe to receive practical updates that help you stay organized and prepared throughout the year.
Sources
IRS guidance
- IRS: Tax inflation adjustments for tax year 2026, including amendments from the One Big Beautiful Bill
- IRS: Frequently Asked Questions on Gift Taxes
- IRS: About Form 709, U.S. Gift (and Generation-Skipping Transfer) Tax Return
- IRS: Instructions for Form 709
- IRS: About Form 8892, Extension of Time to File Form 709
- IRS Publication 970, Tax Benefits for Education
- IRS Publication 551, Basis of Assets
- IRS: Applicable Federal Rates (AFRs)
- IRS Topic No. 553, Tax on a Child’s Investment and Other Unearned Income (Kiddie Tax)
Internal Revenue Code and Treasury Regulations
- 26 U.S.C. Section 529, Qualified Tuition Programs
- 26 U.S.C. Section 1014, Basis of Property Acquired from a Decedent
- 26 U.S.C. Section 1015, Basis of Property Acquired by Gift
- 26 U.S.C. Section 1274, Applicable Federal Rate
- 26 U.S.C. Section 2001, Rate Schedule
- 26 U.S.C. Section 2502, Rate of Gift Tax
- 26 U.S.C. Section 2503, Taxable Gifts and Annual Exclusion
- 26 U.S.C. Section 2513, Gift Splitting by Spouses
- 26 U.S.C. Section 2523, Gift to Spouse
- 26 U.S.C. Chapter 14, Special Valuation Rules (Sections 2701 to 2704)
- Treasury Regulation 20.2010-1, Unified Credit and Anti-Clawback Rule
- Treasury Regulation 25.2503-6, Tuition and Medical Expense Exclusion
State and other federal sources
- Georgia Department of Revenue: Estate Tax FAQ
- 42 U.S.C. Section 1396p, Medicaid Transfer of Assets Rules
Published by Pantana CPA, Acworth, Georgia | Accounting Services | Bookkeeping | Tax Compliance | Payroll Last – Updated: October 29, 2026 Learn more about our services →
This article is provided for informational purposes only and does not constitute legal or tax advice. Tax laws are complex and individual circumstances vary. The information contained here reflects general principles and may not apply to your specific situation. Pantana CPA recommends consulting directly with a licensed CPA or qualified tax professional regarding your particular facts. IRS procedures, deadlines, and relief programs are subject to change.
Let's Get Your Financials In Line With Your Goals
Continue Reading
2026 Year-End Tax Planning for Business Owners: 12 Proven Moves to Protect Your QBI Deduction and Avoid a Costly Tax Surprise
The Premium Tax Credit in 2026: Who Qualifies, Who Gets the Subsidy, and the Warnings Every Taxpayer Should Hear
You Own a Business Overseas – A Guide to what you need to know
You Started an LLC. Did You Tell Your CPA? What Your Accountant Needs to Know (and Why It Matters)
Equipment Purchases Can Cut Your 2026 Tax Bill
Can You Legally Avoid Paying Taxes?
Last-Minute Tax Tips: Why a Tax Pro Matters Most | Pantana CPA