How Rental Properties Are Reported on your Taxes without Income

The Vacant Rental Tax Checklist
Rental Properties without Income
What landlords need to know when a rental property sits vacant, and why a $0 rent check does not mean a $0 tax deduction.
Every year, Pantana CPA fields the same phone call from a new landlord: the property is sitting empty, the mortgage payment still cleared the bank on the first, and the property owner wants to know whether any of it counts on their tax return. The short answer is yes. The longer answer, the one that actually saves clients money, depends on why the property was vacant, how long it sat that way, and whether it was genuinely available for rent the whole time.
The Problem: Expenses Without a Rent Check
Owning a rental property is supposed to bring tax benefits. Depreciation, mortgage interest, property taxes, insurance, repairs: all of it is designed to offset rental income. The complication shows up the moment income disappears. A property between tenants, a renovation that runs long, a first-year landlord still finding a tenant: all of these create a stretch of time where money is going out and nothing is coming in.
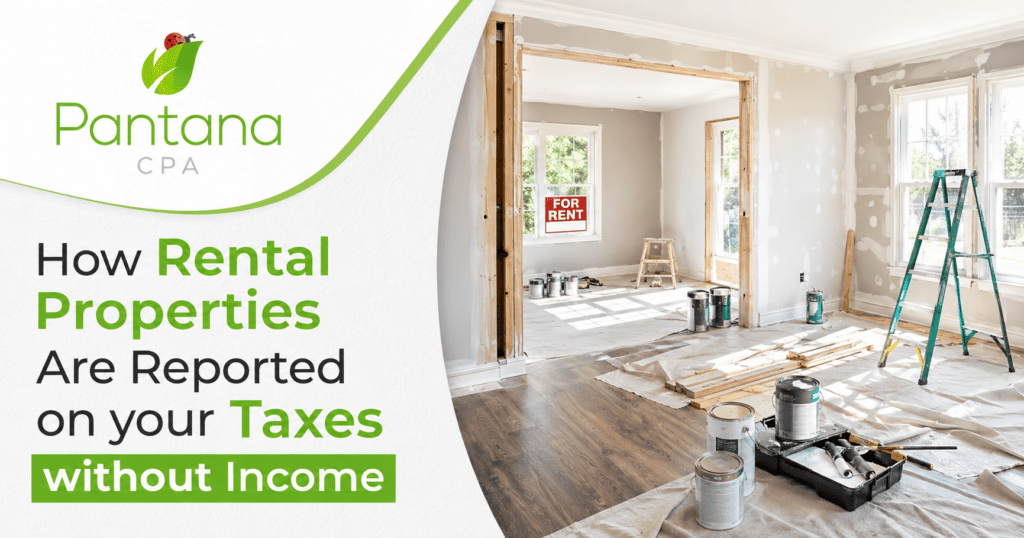
According to the IRS, that gap does not disqualify the expenses. Publication 527 states plainly that if a property is held for rental purposes, an owner may be able to deduct ordinary and necessary expenses, including depreciation, for managing, conserving, or maintaining the property while it is vacant. The one thing the IRS will not allow is a deduction for the rent that was never collected: the loss of rental income itself during the vacant period is not deductible, since a cash-basis taxpayer never reported that income in the first place.
The Test That Actually Matters: “Held Out For Rent”
The deciding factor is not whether a tenant is signing a lease this month. It is whether the property is genuinely being marketed and made available to rent. A property listed with a property manager, advertised on Zillow or a local MLS, and priced at fair market rent qualifies as “held for rental purposes” even with zero tenants in the unit. A property sitting empty because the owner has not gotten around to listing it, or is quietly using it themselves on weekends, does not.
This distinction shows up constantly with new landlords who inherit a property or convert a former primary residence into a rental. The clock on deductible expenses starts when the property is ready and available to rent, not when the first rent check clears.
Where It Gets Reported
Rental income and expenses, or in this case expenses without income, are reported on Schedule E (Form 1040), Supplemental Income and Loss, exactly the same as an occupied property. Per IRS Topic no. 415, mortgage interest, real estate taxes, casualty losses, maintenance, utilities, insurance, and depreciation all reduce the amount of rental income subject to tax
, and that same schedule is where the resulting loss lands.
A Real Example
Consider a single-family rental renting for $1,800 a month. The previous tenant moves out in January. The owner repaints, replaces the flooring, and lists the property with a local property manager the same week. It takes until May to find a qualified tenant, so the property sits vacant and marketed for four months.
During those four months, the owner still pays:
- Mortgage interest: roughly $650 a month
- Property taxes: prorated at about $220 a month
- Insurance: $95 a month
- Utilities kept on for showings: $110 a month
- Property management marketing fee: a flat $300 for the listing period
That is roughly $4,600 in expenses before the first rent check ever arrives, on top of a full year of depreciation calculated over the property’s 27.5-year residential recovery period. None of those four vacant months produce a single dollar of rental income, but every one of those expenses is still deductible on Schedule E for the year, because the property was actively held out for rent the entire time.
[fl_builder_insert_layout id=2985] What Happens When Expenses Create a Loss
Once total deductions exceed total rental income for the year, the property produces a loss. Rental real estate is generally treated as a passive activity under the tax code, so losses are usually limited to offsetting passive income first. For most landlords who are not real estate professionals, the relevant relief valve is the special $25,000 allowance under IRC Section 469(i).
An owner who actively participates in managing the property, meaning they approve tenants, set rental terms, or approve repairs even through a property manager, can generally deduct up to $25,000 of rental losses against ordinary income each year. That allowance is reduced by 50% of the amount that modified adjusted gross income exceeds $100,000, and it phases out completely once MAGI reaches $150,000. A landlord with $120,000 in wages and a $31,000 rental loss, for example, could deduct roughly $15,000 of that loss in the current year and would carry the remaining amount forward to future tax years, per the worked example in IRS Publication 925, Passive Activity and At-Risk Rules.
Losses that cannot be used in the current year are not lost. They carry forward and can offset future rental income, or offset gain when the property is eventually sold. This is one of the most overlooked parts of the tax code for new landlords: a “wasted” vacant year on paper is often banking a deduction for a future year.
The Exception That Trips Up First-Year Landlords
There is one scenario where none of the deductions above apply: personal use. If a dwelling is used personally for more than 14 days, or more than 10% of the days it is actually rented at fair value, whichever is greater, the property is treated as a residence rather than a rental for tax purposes and deduction rules change significantly. This most often catches lake house and vacation property owners who rent the property out part of the year and use it themselves the rest. That situation calls for a separate conversation, since it changes which expenses are deductible and how they are limited.
Why This Matters More in a Vacant Market
New landlords are the ones who run into this most often, especially anyone who bought a property expecting immediate cash flow. A property between tenants for even a few months, a renovation that runs past its timeline, or a first listing that takes longer than expected to fill can all create a stretch of the year with real expenses and no rent. Handled correctly, that period still produces a deduction. Handled incorrectly, either by failing to claim vacant-period expenses or by claiming expenses on a property that was never actually marketed for rent, it can either cost a landlord money or create exposure in an audit.
Why It Matters Now: Vacancy does not pause the tax code. A rental property that is genuinely listed and available still generates deductible expenses even at $0 rental income, and those deductions can turn into a carryforward that offsets income for years to come.
Frequently Asked Questions
Can I deduct rental property expenses if I had no rental income this year?
Yes, as long as the property was held out for rent, meaning it was available, marketed, and priced at fair market rent. Mortgage interest, property taxes, insurance, maintenance, utilities, and depreciation can all still be deducted on Schedule E even in a year with zero rental income.
What happens if my rental expenses create a loss with no income to offset?
The loss is generally treated as a passive loss. Active participants can use the $25,000 special allowance under Section 469(i) to offset ordinary income, subject to phaseout between $100,000 and $150,000 of modified adjusted gross income. Any loss that cannot be used in the current year carries forward to future tax years.
Does a vacant rental property still qualify for depreciation?
Yes. Depreciation continues on a residential rental property placed in service, over its 27.5-year recovery period, whether or not it is occupied during the year, as long as it remains held for rental purposes and has not been converted to personal use.
What disqualifies a vacant property from these deductions?
Two things most commonly disqualify a property: personal use beyond the 14-day/10% threshold, and simply not marketing the property for rent. A property sitting empty without being listed, priced, or shown to prospective tenants is not considered held out for rent, and the IRS can challenge deductions claimed during that period.
The Bottom Line
A vacant rental property is not a tax dead end. It is a timing issue, and timing issues are exactly what a tax professional is for. Pantana CPA works with landlords to document the “held for rent” status correctly, capture every deductible expense during vacant months, and carry forward losses that would otherwise sit unused.
Stop scrambling and stay prepared year-round.
Schedule a consultation and get a clear plan to keep your bookkeeping, payroll, and taxes under control.
Sources:
IRS Topic no. 415, Renting Residential and Vacation Property
IRS Publication 527, Residential Rental Property
IRS Publication 925, Passive Activity and At-Risk Rules
Published by Pantana CPA, Acworth, Georgia | Accounting Services | Bookkeeping | Tax Compliance | Payroll Last – Updated: July 30, 2026
This article is provided for informational purposes only and does not constitute legal or tax advice. Tax laws are complex and individual circumstances vary. The information contained here reflects general principles and may not apply to your specific situation. Pantana CPA recommends consulting directly with a licensed CPA or qualified tax professional regarding your particular facts. IRS procedures, deadlines, and relief programs are subject to change.
Let's Get Your Financials In Line With Your Goals
Continue Reading
2026 Year-End Tax Planning for Business Owners: 12 Proven Moves to Protect Your QBI Deduction and Avoid a Costly Tax Surprise
Giving Inheritance While You Are Still Living: The 2026 Tax Playbook Families Are Asking About
The Premium Tax Credit in 2026: Who Qualifies, Who Gets the Subsidy, and the Warnings Every Taxpayer Should Hear
You Own a Business Overseas – A Guide to what you need to know
You Started an LLC. Did You Tell Your CPA? What Your Accountant Needs to Know (and Why It Matters)
Equipment Purchases Can Cut Your 2026 Tax Bill
Can You Legally Avoid Paying Taxes?